August 28, 2026 · 6 min read
The Financing Timeline Behind a Luxury Home Purchase
A luxury home purchase brings lending, valuation and completion into one timeline, with distinct checkpoints that are easier to understand before a closing date approaches.
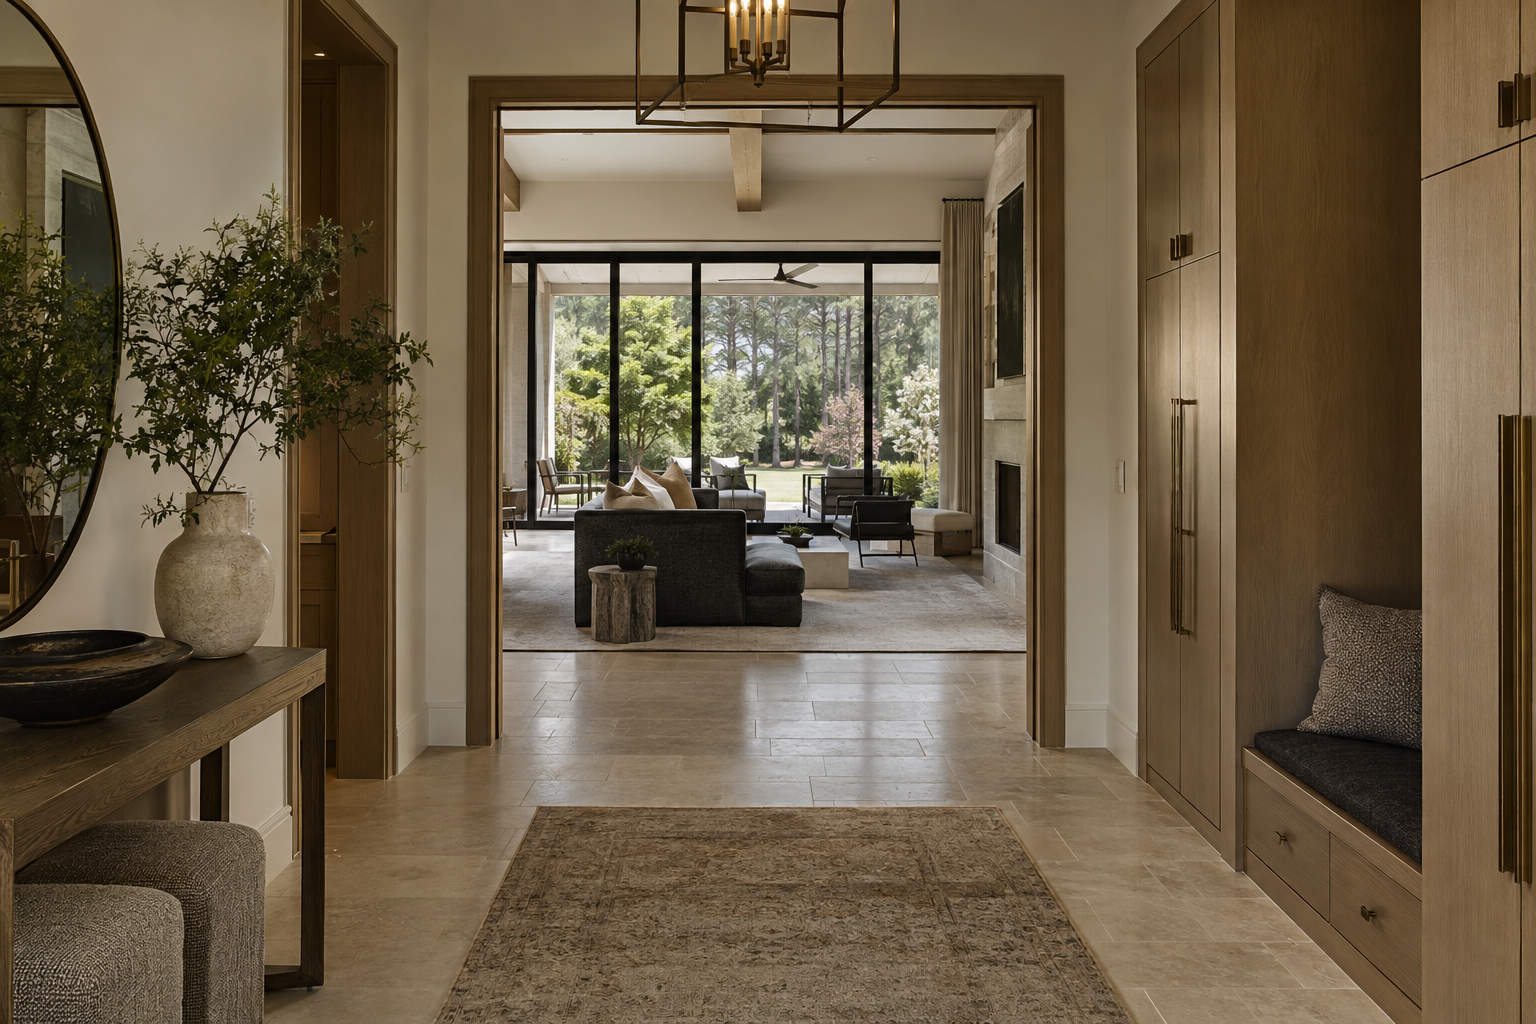
Luxury new construction financing brings together two different ways of reading a residence. A buyer sees proportion, daylight, materials and the relationship between rooms. A lender considers the borrower, the property’s documented value and the conditions required to fund a purchase. Both perspectives matter, but they do not measure the same things in the same way.
For a design-led residence in the Charlotte region, the process is easier to understand when three threads remain distinct: jumbo loan underwriting, appraisal and closing readiness. This overview explains how those threads intersect; it is general information, not financial or legal advice. Requirements and timing depend on the lender, loan program, purchase agreement and property.
How Luxury New Construction Financing Is Structured
Purchasing a newly built residence from a developer is different from borrowing to fund its construction. With a purchase mortgage, the buyer’s loan generally funds at closing, subject to the lender’s requirements. The developer’s financing for the building process is a separate matter.
Peters Signature Homes designs and builds complete residences and offers them for purchase. That distinction frames the lending conversation around acquiring a home rather than managing construction draws. A residence’s stage of completion can still affect the documents, inspections and scheduling involved in a purchase loan.
A finished home gives the buyer and appraiser something tangible to examine. Room dimensions, ceiling transitions, cabinetry, exterior masonry and the connection to outdoor living areas are visible rather than represented only in drawings. Physical completion, however, does not automatically establish that every lending or closing condition has been satisfied.
The purchase agreement and the lender’s requirements govern separate parts of the process. A contractual closing date is not, by itself, confirmation that a loan is ready to fund.
What Makes a Mortgage a Jumbo Loan
A jumbo mortgage generally refers to a loan amount above the applicable conforming loan limit. That limit is not the same as a home’s price, and it can change by year and location. A luxury residence does not automatically require a jumbo loan; the amount borrowed determines whether the relevant limit is exceeded.
Because jumbo products fall outside standard conforming loan limits, requirements can vary substantially among lenders. Income documentation, assets, credit history, existing obligations and the relationship between the loan amount and the property’s value all enter the review. Some programs also require documented reserves remaining after closing.
For buyers whose finances include business ownership, variable compensation or multiple income sources, documentation may be more involved than a salary statement alone. Underwriters evaluate the continuity and acceptability of income under their institution’s rules. A substantial asset balance does not necessarily remove the need to document where funds originated or how they can be accessed.
Prequalification, preapproval and final approval also describe different stages, with terminology varying by lender. An early assessment may establish a preliminary borrowing framework, but it is not an unconditional commitment to fund. Property review and updated borrower information can remain outstanding well into the transaction.
How an Appraisal Reads Architectural Quality
An appraisal is an independent opinion of value prepared for a defined purpose. For mortgage lending, it helps the lender evaluate the property securing the loan. It is not a design critique, a home inspection or a promise that the contract price will be supported.
In a luxury residence, some of the most compelling qualities are also difficult to isolate in a comparison. A carefully proportioned stair hall, continuous white oak flooring or stone installed with disciplined vein alignment may contribute to an overall impression of quality. Those choices do not necessarily receive separate, dollar-for-dollar recognition in the valuation.
Appraisers consider relevant market evidence alongside property characteristics. Depending on the assignment, those characteristics can include location, site, size, condition, construction quality, room utility and amenities. Comparable sales need not be identical, but their differences require analysis. When closely comparable residences are scarce, the work may become more complex.
Clear property information can help make the residence legible. Accurate plans, specifications and descriptions of completed features provide context for what is being evaluated. They do not dictate the result. Emerald & Oak Design is the separate, exclusive design firm for Peters Signature Homes; design authorship and appraisal methodology nevertheless remain distinct subjects.
A lower-than-expected appraisal can affect the lender’s calculations and the transaction’s next steps. Any response depends on the loan terms and purchase agreement. Lenders can explain their valuation review procedures, while qualified transaction professionals can address contractual questions.
When Completion and Documentation Meet
New construction introduces a distinction between work that appears finished and completion that has been documented for a particular purpose. A beautifully resolved kitchen may be ready to photograph while an administrative item remains open. Conversely, an occupancy document does not establish that every lender-specific condition has been met.
Depending on the property’s status and the loan program, an appraisal may be completed subject to specified work being finished. The lender may then require a completion report or other evidence before funding. A residence already complete may avoid that particular sequence, but the lender determines the applicable requirements.
Appraisal, inspection, occupancy approval and the buyer’s final walkthrough serve different functions. The appraisal addresses value for its intended use. An independent inspection evaluates conditions within its scope. Local authorities administer applicable occupancy requirements. The walkthrough is an opportunity to observe the home’s condition in relation to the transaction.
These steps can overlap on a calendar without replacing one another. Their distinct purposes explain why a home can feel entirely ready while a closing file still needs attention.
Why the Closing Calendar Has Several Clocks
The financing timeline is not a single countdown. Underwriting, appraisal scheduling, title work, insurance documentation and completion verification each have their own dependencies. A delay in one can affect the point at which the lender authorizes closing or funding.
An interest-rate lock has a separate timetable. Its duration, conditions and any extension provisions come from the lender. A proposed closing date and a lock expiration date may align initially without remaining aligned if the transaction changes. The lender is the appropriate source for an explanation of those terms and any associated costs.
Changes in the borrower’s financial circumstances can also prompt further review. Updated account statements, employment verification or explanations of transfers may be requested near closing. Final approval therefore reflects both the property file and the borrower file, not merely the passage of time since an application was submitted.
The useful distinction is between an expected milestone and a confirmed one. An appraisal appointment is not a completed report; a completed report is not necessarily lender acceptance; and lender acceptance of the property is not the same as final authorization to fund.
Understanding the Sequence Behind the Purchase
Architecture rewards close observation, and a purchase benefits from a similarly clear reading of its sequence. The residence, the valuation and the financing each have their own evidence of readiness. Understanding those differences helps explain why material completion and transaction completion do not always arrive together.
For a buyer considering a design-led home, financing need not obscure the qualities that made the residence compelling. It is a parallel process, with its own vocabulary, documentation and professional responsibilities.
To explore Peters Signature Homes, view available residences or send an inquiry about the homes and the purchase process.
Journal entries are general editorial writing. They are not offers, advice, or statements about any particular residence, price, availability or transaction. Imagery accompanying an entry is a conceptual visualization created for illustration and does not depict an actual property, and no residence, specification or figure described here has been verified as part of a listing.
Entity Relationship Disclosure
Peters Signature Homes, Inc. is a separate legal entity engaged in the development and sale of luxury speculative residences. Peters Signature Homes does not provide custom-homebuilding, renovation, or build-on-your-lot services.
References on this website to designers, builders, brokers, architects, engineers, consultants, subcontractors, suppliers, manufacturers, developers, lenders, communities, or other businesses identify their respective roles only and should not be interpreted as establishing a partnership, joint venture, agency relationship, guaranty, or assumption of another party's obligations unless expressly stated in a written agreement.
Each company or professional is responsible for its own services, representations, contractual obligations, licenses, insurance, warranties, acts, and omissions to the extent provided by applicable law and contract.
No company identified on this website should be considered a contracting party with a purchaser solely because it is referenced, credited, linked, or identified as having participated in the design, construction, marketing, sale, furnishing, financing, or presentation of a residence.
Company relationships · Legal disclosures · Property disclaimer